Who Pays When an AI Agent Books the Wrong Trip? Citi Has an Answer
When an autonomous artificial intelligence agent makes a critical error—such as booking the completely wrong itinerary, selecting the wrong dates, or reserving a non-refundable room at the wrong destination—someone ultimately has to bear the financial burden of the mistake. According to banking giant Citi, that responsibility should rest squarely on the technology company behind the agent, rather than falling on the shoulders of the hotel, the airline, the consumer, or the credit card issuer.
The question of accountability is rapidly transforming from a theoretical academic discussion into one of the most pressing commercial and legal hurdles in modern commerce. As artificial intelligence systems evolve from simple text-generating chatbots into autonomous transaction-executing agents capable of managing consumer finances and booking complex travel arrangements, the financial services and travel industries are grappling with an unprecedented realignment of risk.
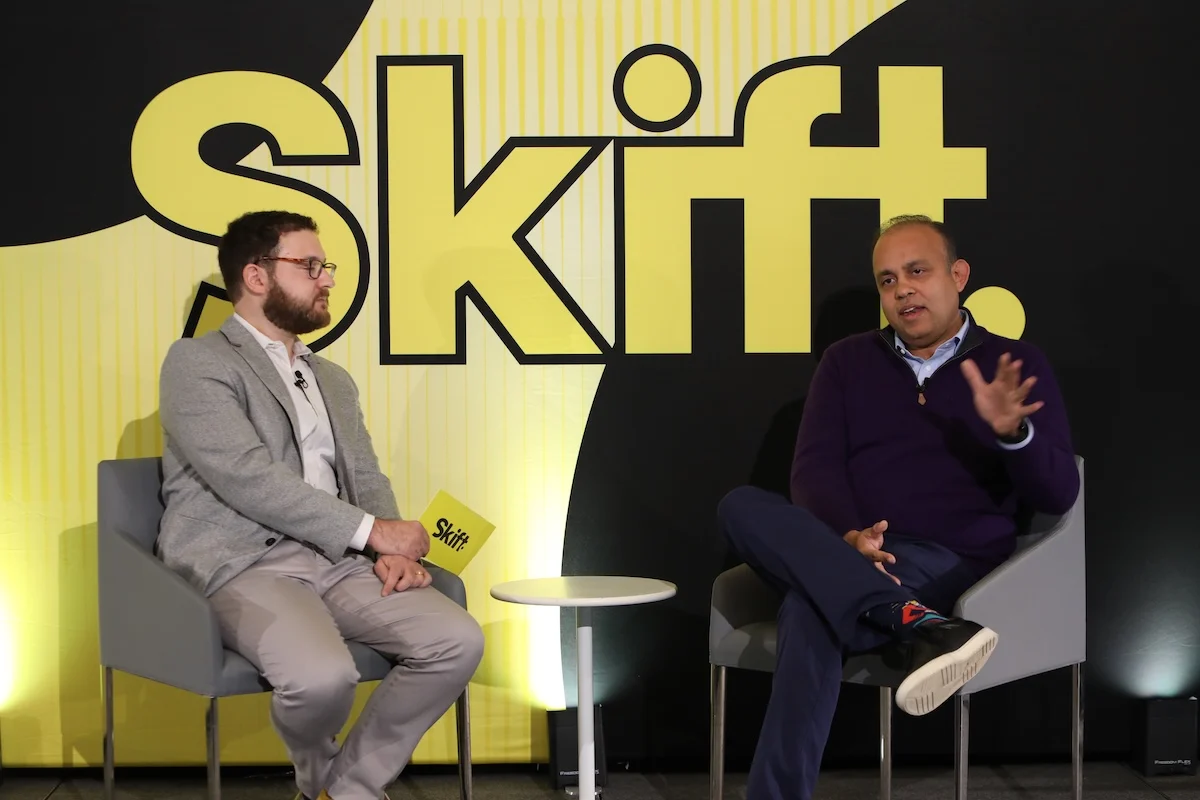
Addressing this burgeoning challenge at the Skift Commerce Summit in New York City, Abhinav Anand, Citi’s head of value cards, lending and commerce for U.S. consumer cards, outlined the institution’s perspective on the matter. Speaking candidly about the intersection of financial technology, artificial intelligence, and travel logistics, Anand highlighted that defining where accountability lies is the single most urgent dilemma facing the entire ecosystem.
"Who takes the agent liability is the biggest question banks, payment networks, merchants and AI companies are trying to answer," Anand told attendees at the Wednesday event.
As consumers increasingly delegate tedious administrative tasks—such as comparing flight schedules, coordinating multi-city hotel stays, and processing payments—to autonomous software agents, the margin for error carries tangible financial consequences. If an autonomous agent misinterprets a user’s prompt and purchases an expensive, non-refundable ticket for the wrong week, traditional chargeback mechanisms and consumer protection frameworks do not neatly apply. Merchants argue they fulfilled an order placed by valid credentials, banks point out that the cardholder did not directly authorize the specific transaction, and consumers demand reimbursement for a mistake they did not manually make.
In Citi’s view, however, the path forward requires establishing a direct chain of responsibility tied to the creators of the software. Anand articulated that liability should fall "to the agent themselves, the company that is actually coming with the agent."
This viewpoint introduces a radical shift in how software developers and technology platforms might operate in the financial and travel sectors. Rather than acting merely as neutral software providers connecting users to online travel agencies and airlines, tech companies deploying autonomous transactional agents could be required to shoulder the financial guarantees associated with their products’ execution errors.
To bridge the gap between traditional payment rails and emerging autonomous commerce, industry stakeholders are already exploring structural frameworks to enforce this accountability. One potential mechanism under discussion involves the major payment networks, such as Visa and Mastercard, establishing baseline compliance rules for artificial intelligence applications.
Under such an arrangement, autonomous agents that wish to securely transact on established payment networks might be required to formally accept a predetermined level of liability. If the software makes a flawed booking due to a systemic logic error, hallucination, or misinterpretation of user intent, the developer would be contractually and financially on the hook to resolve the dispute, compensate the merchant, or refund the consumer. This approach would protect traditional financial institutions from absorbing losses driven by third-party software failures while assuring merchants and travel providers that legitimate transactions executed by AI will not leave them vulnerable to unpredictable chargeback disputes.
The debate comes at a critical juncture for the travel industry, which has spent the past several years aggressively modernizing its digital infrastructure to accommodate automated booking tools, application programming interfaces, and generative artificial intelligence tools. Travel providers are eager to capture high-intent consumer demand driven by conversational search and automated planning assistants, but they remain fiercely protective of their revenue streams against the risks of automated fraud, systemic booking errors, and mass cancellations driven by faulty software.
As technology companies race to deploy the next generation of consumer-facing digital assistants, the regulatory and commercial frameworks governing AI liability remain largely undefined. However, remarks from major financial institutions like Citi signal that the financial sector is drawing a hard line regarding where the financial risk must reside as machines begin taking over the checkout counter. The future of autonomous travel booking will depend heavily on whether tech developers are willing to accept the financial weight of their agents’ mistakes in order to participate in the global payment ecosystem.
| Source | : | Open Passport |
| Author | : | Siti Muinah |
| Editor | : | Open Passport Editorial Team |
