Equal Housing Opportunity: What It Means and Who Qualifies for Assistance
That distinction matters profoundly for millions of Americans navigating the housing market. In reality, the Equal Housing Opportunity symbol refers strictly to fair housing principles and protections against unlawful housing discrimination. It is a declaration of compliance with federal laws, not a marker of financial assistance. Conversely, affordable housing programs provide direct economic support and rental subsidies to eligible households who meet specific financial and demographic requirements. While consumers do not need to qualify for fair housing protections—as they are universal rights guaranteed by law—they generally must clear strict eligibility hurdles to receive government housing assistance.
Understanding the dividing line between anti-discrimination protections and economic assistance programs is crucial for anyone currently searching for a home, apartment, or mortgage.
What Does Equal Housing Opportunity Mean?
At its core, Equal Housing Opportunity represents the foundational legal principle that all individuals should have unhindered access to housing without facing discrimination prohibited by federal, state, and local fair housing laws. The iconic logo, typically depicted as a house featuring an equal sign inside its framework, serves as a visual signal that a real estate professional, landlord, or developer supports fair housing practices. It does not indicate that a particular residence is owned by the government, bound by income restrictions, or attached to a subsidy program.
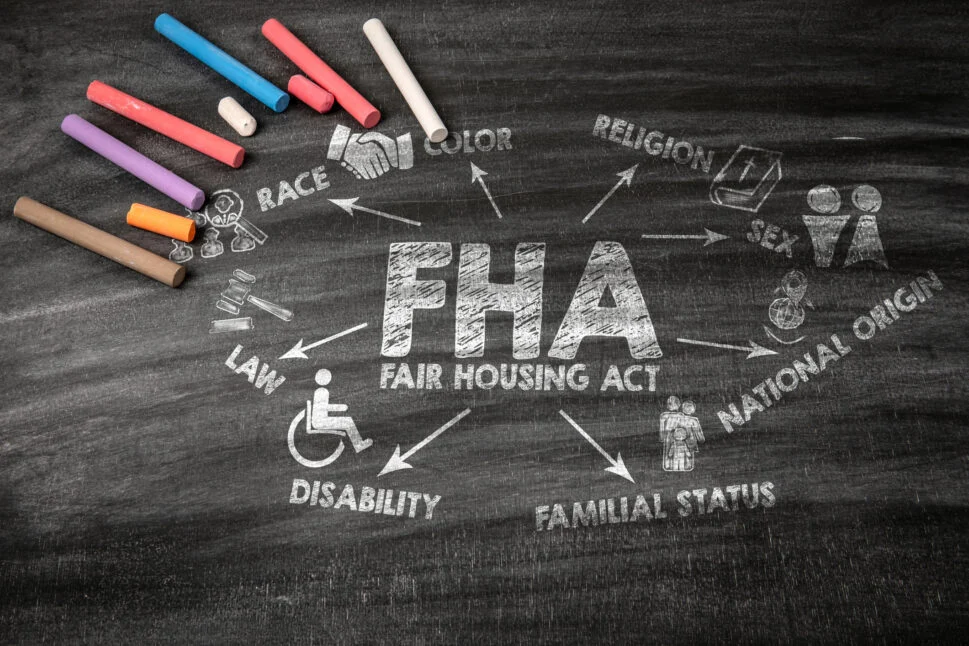
The federal Fair Housing Act lays the groundwork for these protections, explicitly prohibiting housing discrimination based on seven core protected characteristics. These protections apply broadly across the housing continuum, safeguarding individuals when they are renting an apartment, purchasing a home, applying for a mortgage loan, or participating in other housing-related activities, subject to specific legal exceptions outlined in the statute. Furthermore, state and local municipalities frequently enact complementary legislation that provides even broader anti-discrimination protections.
Crucially, fair housing laws do not guarantee that an applicant will be approved for a specific home, apartment, or loan. Housing providers and mortgage lenders retain the legal right to apply neutral, nondiscriminatory eligibility standards to all applicants. For instance, a commercial mortgage lender is fully permitted to evaluate a prospective borrower’s income, existing debts, and credit history to determine financial reliability. However, that same lender is strictly barred from making lending decisions or altering terms based on any of the characteristics protected under the Fair Housing Act.
Are Equal Housing Opportunity Homes Only for Low-Income Households?
The short answer is no. Because Equal Housing Opportunity is a legal standard rather than a housing assistance program, it carries no income qualifications whatsoever. The robust fair housing protections associated with the term are not restricted to low-income earners, first-time homebuyers, or applicants working to rebuild poor credit scores. An ordinary, market-rate home listing routinely displays the Equal Housing Opportunity logo even when the property commands top-dollar market rent and features zero government subsidies or affordability restrictions.
For consumers seeking financial relief or help paying rent, the relevant inquiry shifts entirely to which specific assistance programs match their financial profile. The major federal rental assistance landscape is dominated by public housing, Housing Choice Vouchers, and privately owned subsidized housing. Each of these frameworks operates under distinct administrative rules and eligibility criteria.
Privately owned subsidized housing generally encompasses rental properties where government financial interventions help lower rental costs for eligible residents. Under various programs overseen by the U.S. Department of Housing and Urban Development, financial assistance is tied directly to specific properties or apartment complexes rather than issued to tenants as a portable benefit. Property owners and management companies handle local applications and verify whether households qualify under the guidelines of that specific program. Some subsidized apartments calculate a tenant’s monthly rent as a percentage of household income, while other affordable properties rely on fixed income restrictions and rent caps, meaning qualification rules can vary significantly from one property to the next.
Public Housing and the Housing Choice Voucher Program
Traditional public housing operates differently by providing federally funded rental options specifically tailored for eligible low-income households, including families, older adults, and individuals with disabilities. Unlike privately owned subsidized developments, public housing is typically managed directly through a network of local public housing agencies, commonly known as PHAs. These local agencies receive federal funding and administer housing units in accordance with strict program regulations.
Eligibility for public housing depends heavily on factors such as total household income, household composition, and citizenship or eligible immigration status. Even for households that meet these baseline criteria, units are rarely available on demand. The total inventory of public housing is inherently limited, forcing local agencies to maintain extensive waiting lists or temporarily close applications entirely when demand outpaces available capacity.
Meanwhile, the Housing Choice Voucher Program—widely recognized as Section 8—takes a different approach by helping eligible households afford housing within the private rental market. Rather than requiring participants to reside in a designated public housing complex, voucher holders are generally empowered to search for any private rental property that meets program standards. If a landlord agrees to participate, the local PHA pays a direct housing subsidy to the landlord on the tenant’s behalf, while the household covers the remaining balance of the rent.
However, holding a voucher does not mean every apartment on the open market qualifies. The rental unit must satisfy rigorous program requirements, including specific housing quality inspections and rent reasonableness standards, and the household must successfully navigate the PHA’s approval procedures. Furthermore, because national demand for vouchers routinely outstrips federal funding allocations, waiting lists can remain open for years in many communities. In certain jurisdictions, eligible participants may also explore a specialized Housing Choice Voucher homeownership option, which permits qualifying first-time buyers to apply voucher assistance toward homeownership expenses, subject to strict local availability and counseling requirements.
Navigating Eligibility, Financial Screening, and Immigration Status
Qualifying for housing assistance ultimately depends on the specific rules governing each program rather than the presence of an Equal Housing Opportunity logo. For both public housing and Housing Choice Vouchers, local PHAs carefully evaluate household income levels, family size, and citizenship status against local benchmarks established by HUD. Because these income limits are adjusted regionally based on local economic data, a household that qualifies easily in one city may exceed the threshold in another.
Questions regarding financial history often arise among prospective applicants, particularly concerning credit scores. Housing assistance programs do not operate identically to conventional mortgage underwriting. While a voucher applicant’s financial eligibility is anchored primarily to program income rules rather than traditional mortgage credit tiers, local PHAs and private landlords are still permitted to conduct lawful background and financial screenings. Specific rental history markers, criminal background factors, or eviction records can influence admission decisions depending on local and federal guidelines, meaning applicants should always consult directly with housing authorities regarding screening criteria.
Complexities also arise for households that include members with mixed immigration statuses. Federal housing programs enforce strict citizenship and eligible immigration-status rules, but provisions historically exist to accommodate mixed-status households through prorated assistance, allowing eligible members to receive a reduced subsidy. However, these regulations are subject to ongoing administrative review. Federal agencies have pursued regulatory changes aimed at tightening verification procedures and restricting ongoing prorated assistance, emphasizing the importance for affected families to seek up-to-date guidance from housing agencies or legal aid providers before making major housing decisions.
Waiting Lists, Portability, and Ongoing Responsibilities
Securing a spot on a housing assistance waiting list rarely translates to immediate placement. PHAs utilize localized preference systems to prioritize applicants facing acute hardships, such as homelessness, displacement, or severe disability-related housing needs. Consequently, waiting list placement is determined by a combination of local preferences, application timestamps, and local selection methods, such as lotteries.
For those who successfully secure a Housing Choice Voucher, the program offers a degree of geographic flexibility known as portability. This process allows eligible voucher holders to move outside their initial PHA’s jurisdiction and use their assistance in a new area, though strict administrative rules and residency timelines often apply during the first year of participation.
Once housing assistance is established, both tenants and landlords assume ongoing legal and financial responsibilities. Voucher holders must strictly comply with their lease agreements, report changes in household income or composition promptly, and maintain the unit in good standing. Landlords participating in federal programs are similarly bound to maintain properties according to strict housing quality standards. Failure by a landlord to correct identified maintenance deficiencies can trigger enforcement actions by the PHA, underscoring the need for open communication between tenants, landlords, and local housing administrators as participants navigate the complexities of the modern housing market.
| Source | : | Open Passport |
| Author | : | Evan Lee Salim |
| Editor | : | Open Passport Editorial Team |
