Reinventing Employee Benefits: Why Benefitbay’s Brandy Thompson Says ICHRA Is the Fix HR Leaders Need
For many human resources directors and benefits leaders, the annual corporate benefits renewal has long felt like a ritual of diminishing returns. Year after year, healthcare costs climb steadily upward, employee satisfaction stagnates or declines, and the options on the table look largely identical to the packages offered five years prior. Traditional group health plans have left organizations trapped in an escalating cycle of financial exposure and inadequate coverage solutions.
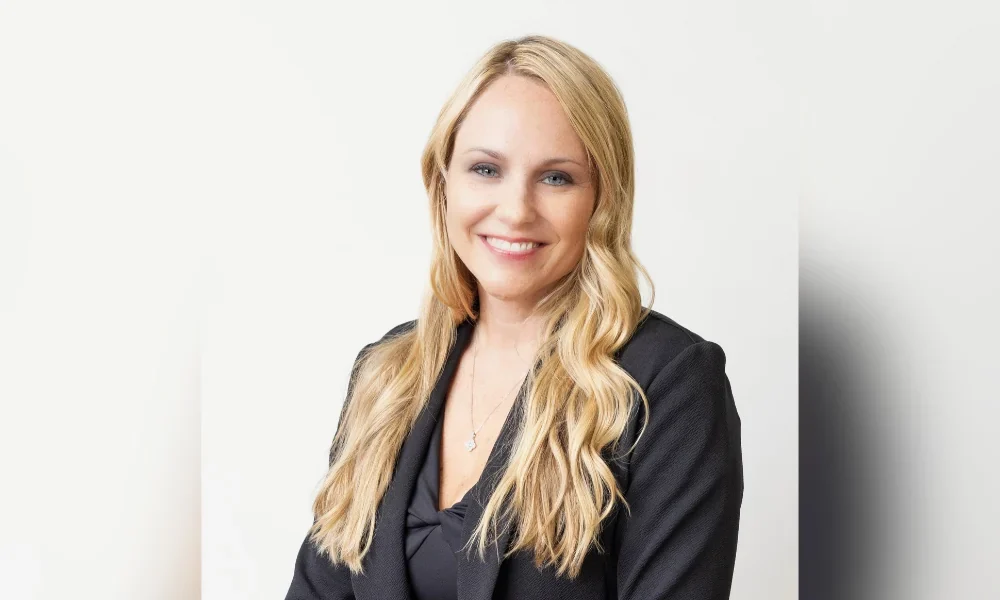
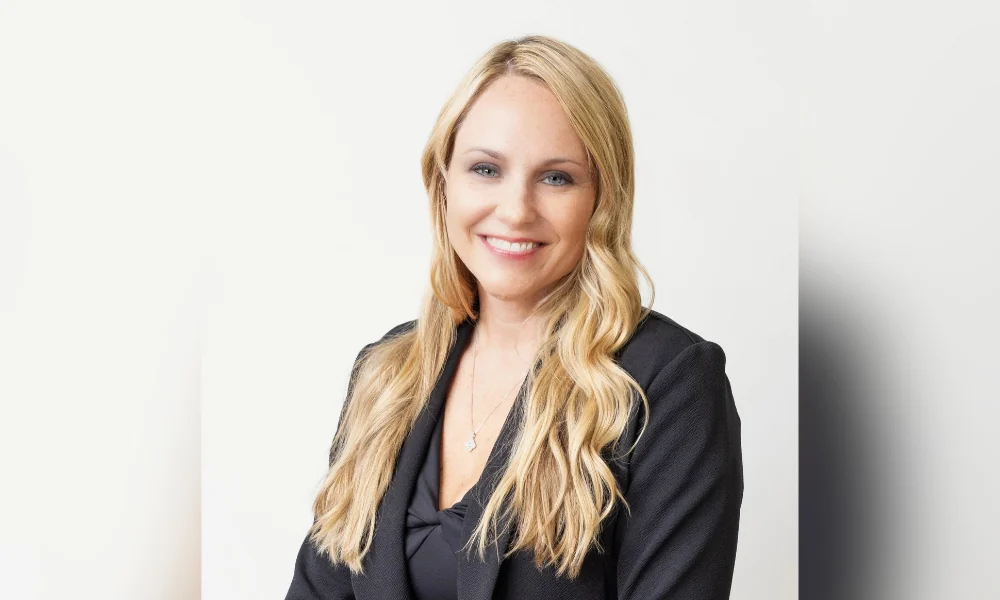
Brandy Thompson, co-founder and CEO of Benefitbay, believes that the individual coverage health reimbursement arrangement—increasingly referred to by the current administration as a "CHOICE arrangement"—presents the structural fix that corporate HR leaders have been desperately missing. However, Thompson emphasizes that the primary barrier to widespread adoption is not the product itself. Instead, it is a combination of policy instability and a persistent education gap at the employer level.
According to Thompson, organizations are continually searching for relief through traditional channels, often with disappointing results. Employers are simply experiencing unsustainable financial outcomes regardless of the specific tool they pull out of their traditional chest, she notes. Many companies have turned to self-insurance models or inserted various point solutions into their benefits stack in hopes of reining in costs, yet these strategies have frequently fallen short of expectations.
What ICHRA Actually Means for HR Teams
Under a traditional group health plan, an employer typically selects a very limited number of group options and absorbs the vast administrative and financial exposure when those plans ultimately underperform or experience heavy utilization.
An individual coverage health reimbursement arrangement changes this dynamic fundamentally. Under an ICHRA model, the employer establishes a defined financial contribution. This allowance can be tailored and varied based on geography, employment classification, or specific rating areas. Employees then use this designated allowance to purchase individual health insurance coverage on the open market, selecting a plan that precisely fits their own personal health needs and unique family situation.
Rather than struggling to manage a rigid, one-size-fits-all plan across a diverse workforce with widely divergent healthcare needs, modern HR leaders can finally offer genuine choice while effectively containing their cost exposure. Premium rate increases become isolated by local geography rather than being absorbed across the entire corporate population.
Thompson points out that just because a steep 13 percent rate increase occurs in a certain regional market, it does not mean that the employer will experience that same surge across their entire workforce. In traditional group insurance or self-insurance arrangements, one or two high-cost claims throw the entire population out of balance, driving up costs for everyone. With an individual coverage health reimbursement arrangement, those financial fluctuations remain isolated.
Benefitbay, a firm that currently serves approximately 400 companies averaging around 1,000 employees each, has intentionally engineered its platform around the complex operational realities that mid-to-large employers face. These operational needs include seamless Human Resources Information System integrations, Affordable Care Act 1095 tax filing support, variable-compensation eligibility recalculations, and multi-rating-area contribution structures.
Thompson argues that these sophisticated back-end capabilities are precisely what smaller ICHRA platforms—typically built strictly on individual exchange rails—fail to replicate. They are also the exact prerequisites that HR teams at mid-sized and large organizations must have before they can confidently make the strategic switch away from traditional group policies.
Adding another layer of complexity to the landscape is the recent federal rebranding from "ICHRA" to "choice arrangement." This administrative shift has introduced temporary confusion that corporate HR communicators must actively navigate during open enrollment periods. Benefitbay deliberately utilizes both terms in its communications to avoid any potential ambiguity, though Thompson candidly acknowledges that the timing of the rebrand was less than ideal for the broader market.
The industry was just beginning to gain meaningful educational traction around the concept of the individual choice health reimbursement arrangement, Thompson observes, before new terminology was introduced to define what choice actually entails. While understanding the intent behind the administrative update, she notes that the timing has not been particularly helpful for market comprehension.
The Employee Experience Problem ICHRA Is Designed to Solve
For Thompson, however, the most urgent and compelling argument for adopting an individual coverage health reimbursement arrangement extends far beyond mere corporate cost containment. The true driving force is rectifying what the traditional group insurance system does to employees who struggle to afford the coverage forced upon them.
If the workforce remains locked into high-deductible health plans paired with health savings accounts, a worker earning modest wages simply cannot afford to access necessary medical care, Thompson explains. These lower-wage employees frequently delay seeing a doctor until their medical conditions reach advanced stages, such as stage four. Employers must find a way to transition these workers into health plans they can actually afford—plans that may feature zero deductibles and zero copayments, even if they operate within a more narrow network, ensuring that employees will actually utilize primary and preventative care.
The high-deductible health savings account model was originally designed around the tax-deferred savings needs of higher-earning corporate employees. When applied broadly across an entire workforce with vastly disparate income levels, it effectively prices lower-wage workers out of regular healthcare access. This creates a structural inequity that sits squarely within the remit of modern human resources and equitable benefits design.
By removing the rigid constraint of a single corporate-mandated plan, ICHRA allows individual workers to select insurance coverage meticulously calibrated to their actual personal financial situation and healthcare requirements, rather than aligning with the tax planning preferences of the organization’s highest earners.
Furthermore, Thompson highlights an important data privacy dimension that many HR leaders may not have fully considered under traditional group health models. Within a standard group insurance framework, an individual employee’s sensitive health utilization data—including specific prescriptions, medical diagnoses, and detailed claims histories—flows directly back into the employer’s underwriting profile. Under an ICHRA structure, that intrusive link is completely severed.
An individual needs the freedom to manage their health without their employer being involved in the clinical details, Thompson asserts, noting that employees should be able to select coverage based on their personal medical needs and upcoming surgical plans without their employer peering into their private medical data. Benefitbay provides access to licensed advisors for employees navigating sensitive health decisions, such as a cancer diagnosis or a planned procedure, allowing them to make informed choices without disclosing private health information to their internal HR department or corporate benefits broker.
What HR Leaders Should Watch Heading Into 2027
Looking ahead, Thompson identifies administrative and legislative stability as the single most critical lever for accelerating corporate employer adoption of individual coverage health reimbursement arrangements. She expresses cautious optimism that the coming years will deliver that much-needed stability.
The past two open enrollment cycles were heavily overshadowed by significant macroeconomic and political uncertainty. Last year’s enrollment window coincided with a federal government shutdown, while ongoing volatility surrounding Affordable Care Act subsidies, fears of Medicaid funding cuts, and sudden carrier market exits created deep hesitation among employers who were otherwise fully prepared to transition their benefits models.
During open enrollment cycles marked by government instability and volatile subsidy discussions, employers naturally grow cautious, Thompson explains. Administrative policy stability within the individual and ACA insurance markets is ultimately what will drive widespread long-term adoption.
This policy uncertainty has also been compounded by a persistent narrative problem. Employers and employees routinely conflate highly politicized, heavily covered on-exchange subsidy debates with off-exchange employer-sponsored ICHRA access, which operates through an entirely separate regulatory track. The noise surrounding the Affordable Care Act tends to be political and sometimes exaggerated, whereas corporate ICHRA implementation functions independently. HR communications teams will need to address this conflation directly and clearly with their workforces during future open enrollment campaigns.
Nevertheless, Thompson remains optimistic that the broader political landscape will foster a more stable operational environment. The ICHRA framework originated during the first Trump administration and was subsequently expanded under the Biden administration—representing a genuinely bipartisan track record that positions the model well regardless of future shifts in Washington. She expresses confidence that ongoing investments in the healthcare sector and efforts to strengthen the regulatory framework will ultimately produce the market stabilization employers are looking for.
At the ground level, new trends are already signaling a shift in employee sentiment. Dual-ICHRA households—where both spouses work for separate employers that offer individual coverage health reimbursement arrangements—are now actively comparing their respective corporate financial contributions and coverage outcomes during renewal seasons. This level of employee engagement and plan comparison was virtually nonexistent just a few years ago.
As individual coverage health reimbursement arrangements reach a critical mass within the corporate world, employee-driven demand may begin to surface directly at the employer conference table. This shift has the potential to transform the transition from an HR-led administrative rollout into a standard workforce expectation.
For human resources leaders looking to benchmark their current corporate benefits strategies against the rising cost and coverage trends fueling ICHRA interest, independent industry resources such as annual employer health benefits surveys provide valuable peer data on premium growth, shifting deductible levels, and employer cost-sharing trends. Compliance guidance is also readily available through federal regulatory agencies for plan sponsors navigating technical requirements.
In closing, Thompson returns to the fundamental priority that underpins her entire philosophy: care navigation. Giving workers a choice of insurance plan is merely the initial starting point. Organizations must also ensure that clear care navigation support is in place so that individuals can make informed decisions when selecting coverage and successfully manage their healthcare outcomes throughout the year as they access medical services. The communication and support infrastructure built around an ICHRA model is just as crucial as the financial product itself, and organizations that invest heavily in that support infrastructure will ultimately realize significantly better health and financial outcomes for their employees.
| Source | : | Open Passport |
| Author | : | Dwi Wanna |
| Editor | : | Open Passport Editorial Team |
